Statistical Modeling

Senior Economist – Macroeconomic Research – Banking/Financial Services

Job Description: Senior Economist Role Overview: As a Senior Economist, you will play a pivotal role in leading macro and microeconomic research, developing proprietary forecasting models, and delivering actionable insights to senior executive leadership, clients, and external stakeholders. You will translate complex economic data into high impact strategic advice that drives decision making. Key Responsibilities:

Senior Economist – Macroeconomic Research – Banking/Financial Services Read More »

IRB Modeler – Credit Risk Model Validation Specialist – Banking/Financial Services

Role Overview: As a Credit Risk Model Validation Specialist based in Mumbai, you will play a pivotal role in ensuring the integrity and robustness of the bank’s risk management framework. You will be responsible for independently reviewing and challenging complex credit risk models, including PD, LGD, and EAD frameworks, to ensure they remain fit for

IRB Modeler – Credit Risk Model Validation Specialist – Banking/Financial Services Read More »

Arbitrage Fund Manager – Asset Management Firm – IIM/FMS/MDI/XLRI

Role Overview: We are seeking a seasoned Arbitrage Fund Manager to spearhead our arbitrage desk at a leading Asset Management Company in Mumbai. In this high-impact role, you will be responsible for managing large-scale arbitrage portfolios, identifying market inefficiencies, and executing complex derivative strategies to deliver consistent risk-adjusted returns. You will work closely with the

Arbitrage Fund Manager – Asset Management Firm – IIM/FMS/MDI/XLRI Read More »

Assistant Vice President – Model Risk Validation – Banking/Financial Services

Role Overview: The ideal candidate should have experience in Credit Risk Model Development or Credit Risk Model Validation in MNC Banks, Private Sector Banks, Foreign banks, Public Sector banks, or Consulting firms. Credit Risk Methodology: Strong experience and practical in-depth understanding of Credit risk model development and validation methodologies and procedures. Quantitative Background: Strong quantitative

Assistant Vice President – Model Risk Validation – Banking/Financial Services Read More »

Model Risk Validation Role – Credit Risk

Credit Risk Modeling: Strong experience and practical in-depth understanding of Credit risk model development-validation methodologies and procedures. Quantitative Background: Strong quantitative background in Applied Statistics-Mathematics-Operations Research-Economics-Engineering-or related quantitative field. Regulatory Regimes: Strong work experience and practical understanding of at least one or more of the following regulatory regimes: US (FRB-OCC), UK (PRA-ECB), CBUAE (MENA), RBI

Model Risk Validation Role – Credit Risk Read More »

Assistant Vice President – Quantitative Models – Treasury/ Behaviroral Models – Banking/Financial Services

Description: We are hiring for a leading Investment bank based at Mumbai. Experience: 5 – 9 yrs in Model Development/Model Validation for financial Services in treasury models/ with good Python programming skills. Education: Masters / MBA in Economics, Mathematics, Statistics, Finance, Computer science from Tier 1 with good knowledge in Quant/ Treasury Models/ Liquidity models.

Assistant Vice President – Quantitative Models – Treasury/ Behaviroral Models – Banking/Financial Services Read More »

Arbitrage Fund Manager – Asset Management Firm – IIM/FMS/MDI/XLRI

Role Overview: We are seeking a seasoned Arbitrage Fund Manager to spearhead our arbitrage desk at a leading Asset Management Company in Mumbai. In this high-impact role, you will be responsible for managing large-scale arbitrage portfolios, identifying market inefficiencies, and executing complex derivative strategies to deliver consistent risk-adjusted returns. You will work closely with the

Arbitrage Fund Manager – Asset Management Firm – IIM/FMS/MDI/XLRI Read More »

Fedbank Financial Services – Assistant Vice President – Risk Analytics

You will be responsible for driving credit risk analytics, portfolio monitoring, underwriting insights, scorecard development, policy optimization, and risk strategy for the LAP and Gold Loan portfolios. The role requires leveraging data analytics to improve portfolio quality, profitability, collections effectiveness, and customer acquisition while ensuring adherence to regulatory and internal risk frameworks. Portfolio Risk Management:

Fedbank Financial Services – Assistant Vice President – Risk Analytics Read More »

Credit Risk Model Developer – IRB Modelling – Banking & Financial Services

Role Overview: Are you an experienced Credit Risk Model Developer with expertise in IRB (Internal Ratings-Based) Modelling and wholesale credit risk portfolios? We are looking for a skilled professional to develop, calibrate, and implement advanced credit risk models while supporting regulatory compliance under the Basel IRB framework. Responsibilities: – Develop and enhance Probability of Default

Credit Risk Model Developer – IRB Modelling – Banking & Financial Services Read More »

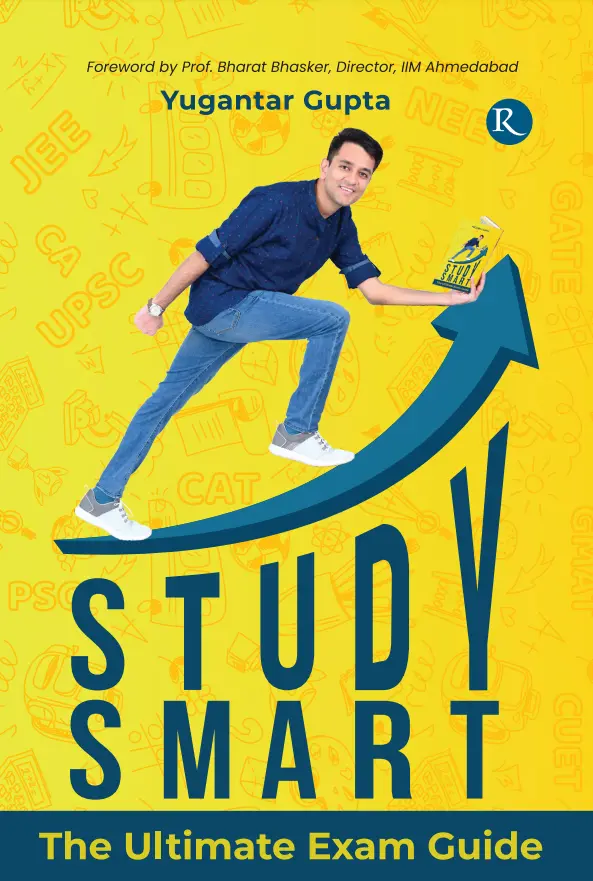
Study Smart: The Ultimate Exam Guide by Yugantar Gupta
Scroll to Top